Michael Yardney , Founder
Please use the menu below to navigate to any article section:
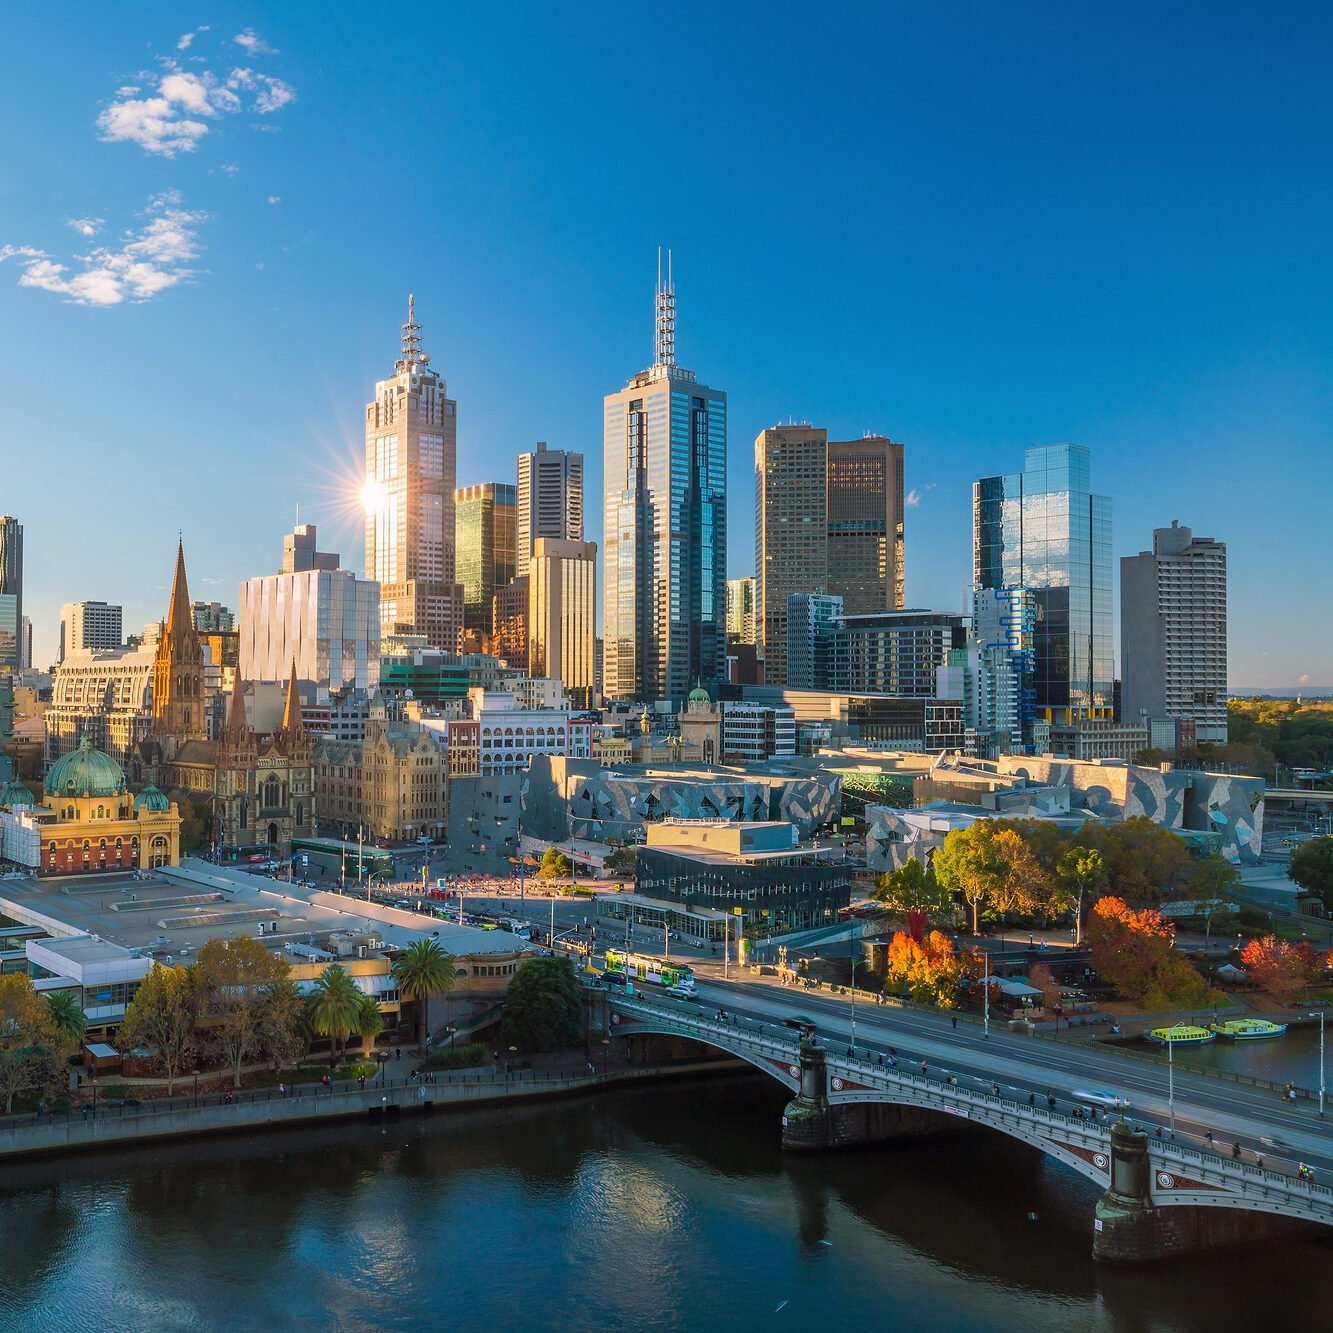
While most of Australia’s big capitals are sliding quickly, Melbourne is easing down at a noticeably slower pace. Home values fell 0.8% in October, roughly half the rate of Sydney and well below Brisbane, Perth and Adelaide.
That relative calm comes with an important caveat. Melbourne values remain 8.2% below their March 2022 record and 7.3% lower than they were five years ago, a reminder of just how subdued the city’s medium-term cycle has been.
The backdrop is a national downturn that has gathered unusual speed. Cotality’s national index fell 1.2% in October, the seventh monthly fall in a row, leaving values 6.7% below the March peak, or about $63,000 lower for the average home.

Across the combined capitals, values have dropped 8.1% in just seven months, the quickest decline over a similar stretch in at least 40 years. Melbourne’s softer trajectory says less about local strength and more about how little froth was built up there in the first place.
The Gentlest Fall Among the Big Capitals
Comparing October’s results with each city’s five-year position tells an interesting story. The markets that ran hardest during the boom have the most room to fall, and they are falling fastest. Melbourne, which largely missed that boom, is falling more slowly but has very little accumulated growth to cushion owners.
| Market | October change | Change over five years |
|---|---|---|
| Melbourne | -0.8% | -7.3% |
| Sydney | -1.6% | -1.5% (versus October 2021) |
| Perth | -1.7% | +68% |
| Canberra | -0.7% | Little changed |
Source: Cotality, November 2026
Five Years Without Growth Leaves a Thin Cushion
Equity is one of the biggest differences between this downturn’s winners and losers. Cotality notes that Perth values could fall 20% from their record and simply return to mid-2025 levels. Melbourne owners have no such buffer. Anyone who bought in the past five years is, on average, sitting on a property worth less than they paid.
The pressure on buyers comes from the same place as everywhere else: the cost of credit. Fittingly, the RBA delivered its latest 25 basis point hike on Melbourne Cup day, its fifth rise of 2026, lifting the cash rate to 4.85%, the highest in 18 years. Annual headline inflation of 4.3% and core inflation of 3.7%, both above the 2–3% target, mean further increases cannot be ruled out.
Rate rises have reduced a median-income household’s borrowing capacity by about 12%, or nearly $90,000, more than the $63,400 fall in the national median home value since March.
In practical terms, Melbourne’s lower prices are being offset by smaller loan approvals, so affordability for borrowers has not improved the way the headline numbers might suggest.
Investor demand, traditionally an important part of Melbourne’s market, has also weakened following the tax policy changes in the federal budget, adding to the drag from higher rates.
Melbourne Renters Still Have Fewer Options Than Most
Rental conditions in Melbourne have loosened, but only a little. The city’s vacancy rate has risen to 1.9%, which is still tighter than the national figure of 2.3%.
Nationally, the trend is clearer. Vacancy is at its highest since January 2022, the month before international borders reopened, and sits just under the 10-year average of 2.4%. It remains well short of the 3.3% average of the decade before COVID, however.
Rent growth has cooled as a result. Seasonally adjusted national rents rose 0.9% over the three months to October, the smallest quarterly gain since January 2025. After a 52% increase over six years, which has added about $245 a week to the median rent, Cotality believes many tenants have simply hit their affordability ceiling. Slowing net overseas migration should also ease demand at the margin.
| Rental measure | Reading |
|---|---|
| Melbourne vacancy rate | 1.9% |
| National vacancy rate | 2.3% |
| National 10-year average vacancy | 2.4% |
| Pre-COVID decade average vacancy | 3.3% |
| National rent growth, past three months | +0.9% |
| National rent growth, past six years | +52% |
Source: Cotality, November 2026
Buyers Have the Leverage, Just Not the Confidence
Melbourne’s estimated home sales are down 25% on a year ago and almost 9% below the five-year average. Fewer transactions, combined with rising stock, have tipped negotiating power firmly towards purchasers.
Across the capitals, homes are now taking a median 39 days to sell, the longest since August 2020. Vendor discounts have widened to 4.7%, the largest since May 2019, and auction clearance rates are holding below 50%. Total listings are at their highest for this time of year since 2019, even with new listings running around 17% below average.
Yet many would-be buyers are waiting. National unemployment has climbed to 4.7%, its highest since 2021, jobs growth has slowed to 1.2% a year, and consumer sentiment remains historically weak.
In a market with longer selling times and wider discounts, use recent comparable sales as your anchor in negotiations rather than the asking price.
Where Melbourne Goes From Here
Cotality expects conditions to remain under downward pressure into next year. Higher rates, reduced borrowing capacity, tighter serviceability, a weaker labour market and soft investor demand are all working against values.
Supporting the market is a persistent shortage of new housing, driven by high construction costs, limited capacity and the complexity of delivering projects, along with population growth that is slower than before but still positive.
Melbourne’s gentler decline may continue to set it apart from the other large capitals. But with little growth banked over the past five years, the direction of inflation, interest rates and jobs will matter just as much here as anywhere.