Brett Warren , National Director – Metropole Group
Please use the menu below to navigate to any article section:
- Start with your budget, not the suburb
- Location: the one thing you can’t renovate
- A top-down system, not a bottom-up hunt
- The property Monopoly board: four types of location
- Our Six-Stranded approach
- Buying cheap versus buying right
- The hidden cost of waiting
- When to buy: reading the property cycle
- Everyone is late to the party
- Think countercyclically
- The bottom line
Where do you start your search for an investment property?
It’s the classic question every property investor asks but here’s the order that builds wealth.
What should I buy, Where should I buy it, and When?
At every seminar we used to run, Michael Yardney would put this question to the room.
Almost without fail, the answer came back: location and while the room was right, because the location matters enormously. there’s a twist.
But before you can think about location, there’s something more fundamental to get right and the order in which you make these decisions.
Getting that right can mean the difference between a portfolio that quietly compounds and grows for decades and one that drifts sideways.

Start with your budget, not the suburb
The first thing to understand is your budget and I don’t just mean a number from the bank.
It’s a combination of two things: your borrowing capacity and your comfort level.
A lender may tell you that you can borrow $1 million, that doesn’t mean you should, as you may only feel comfortable borrowing $800,000, and that’s a perfectly legitimate place to start.
Working out your true budget is critical, because everything that follows flows from it.
Only once that has been modelled and stress tested, then settled, can you sensibly consider location.
Location: the one thing you can’t renovate
If you don’t like grandma’s pink carpet or the shaggy wallpaper, that’s fine, you can change those.
What you can’t change, for the next 20 years, is where the property sits, so you simply must get the location right.
Next comes the type of property.
All things being equal, a house will generally win, but you need to go deeper, and I want think in terms of land value rather than bricks and mortar.
You simply can’t buy a $1 million house in a suburb where the median is $3 million.
So rather than moving further out to get a house, consider a townhouse or a well-located apartment in the better area.
Moving further out means sacrificing location, incomes and demographics and ultimately capital growth and safety.
You’re also sacrificing the land component and its value and that idea sits at the very core of how we approach every purchase.
A top-down system, not a bottom-up hunt
I’ve lost count of the people I’ve spoken to who start their investing journey at the wrong end.
They begin with price, then property type, and only later wonder about the market, while we flip that completely.
Our approach works from the big picture down:
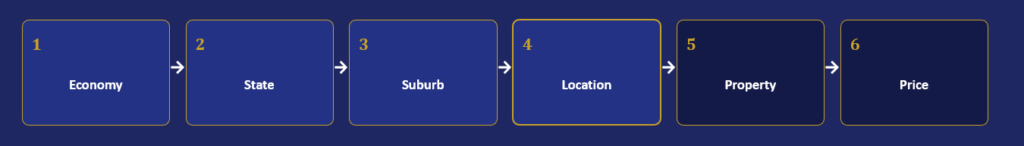
- The economy. Which economies are booming and which are struggling?
- The state. What do the leading indicators, past performance and current conditions suggest about each state’s next phase?
- The suburb. Where can your budget afford the best suburb in the best state?
- The location within the suburb. Which pockets of that suburb are genuinely investment grade?
- The property type.
- The price.
That fourth step is where many investors trip up.
Take New Farm in Brisbane, recently named among the top suburbs in the world.
It is a proven performer and a location that is always high on our list, yet we’d only buy in roughly half of the suburb.
Some parts flood, some are zoned for high-rise apartments and others have major roads and cut through streets.
Picking the best streets within a great suburb matters, because once you’ve bought, you can’t move the property.
We estimate only around 4% of properties on the market at any one time are investment grade.
This top-down process is the funnel we use to find them.
Why so much focus on location?
Because around 80% of a property’s capital growth performance comes from its location, while the remaining 20% comes from the property itself.
The property Monopoly board: four types of location
Think of the market a bit like a Monopoly board. Broadly, we see four kinds of location.
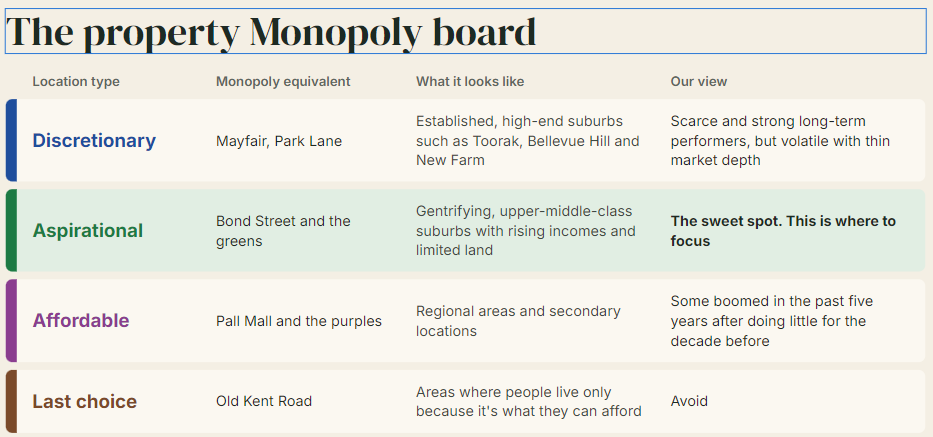
The discretionary suburbs are wonderful, but not everyone can afford a $20 million property, so fewer buyers mean more volatility, so that’s not where we want to be.
Aspirational suburbs have more market depth, greater affordability and less volatility and offer the sweet spot.
Next up, the affordable end deserves a word of caution.
Some of these areas have done exceptionally well over the last five years but looks can be deceiving.
Looking back over the previous decade and many performed very poorly and I expect them to struggle in this part of the cycle, as wages struggle and it takes longer for buyers to rebuild savings.
As for last-choice suburbs, well they are areas to avoid completely.
That is not a judgement of the people who live there, it’s simply the reality of where your investment dollars won’t work as hard.
Our Six-Stranded approach
Once you’re in the right location, every property we consider is tested against six strands.
- It appeals to owner-occupiers. We’ve perhaps glossed over this in the past, but it matters. Owner-occupiers buy with emotion and often pay more, which pushes up values. At this stage of the cycle, with few investors active, they’re the ones putting a floor under the market. Areas without them are far more exposed to falls of 20% to 30%.
- It’s bought below intrinsic value. That’s not the same as below market value, which is hard to achieve in a rising market. It means paying less than replacement cost. In Sydney, building an average two-bedroom apartment now costs around $1 million. Buy a quality one for $850,000 or $900,000 and you’ve got a built-in buffer.
- The land does the heavy lifting. Whether it’s a house, townhouse or unit, the value is in the land. Ideally the land component is above 50% and appreciating. That rules out high-rise towers and most off-the-plan stock, where $200,000 of land might sit under $600,000 of construction.
- It has a proven track record of capital growth. If I’m asking you to hold for 20 years, I want to know what happened over the last 20. Did it only boom recently? How did it fare through the GFC? I’m looking for consistent growth averaging 7% or more per annum.
- It has a twist. I recently explained to a client why their Sydney apartment had outperformed in a suburb full of apartments. It was 10 square metres bigger, had a generous balcony and was walking distance to the train. For apartments, a twist might be a ground-floor courtyard, extra space or separate parking. For houses, it might be development or renovation potential.
- You can add value. Hold a property long enough and you’ll get the chance to manufacture growth through renovation or improvement, while using appreciation and negative gearing as the laws currently allow.
Buying cheap versus buying right
One of the costliest mistakes I see is investors chasing a bargain.
People ask me to find something $50,000 or $60,000 under market value, that then plan to hold it for 10 or 20 years.
Over that horizon, what you pay today matters far less than what you buy.
Consider two properties, each valued at $1 million.
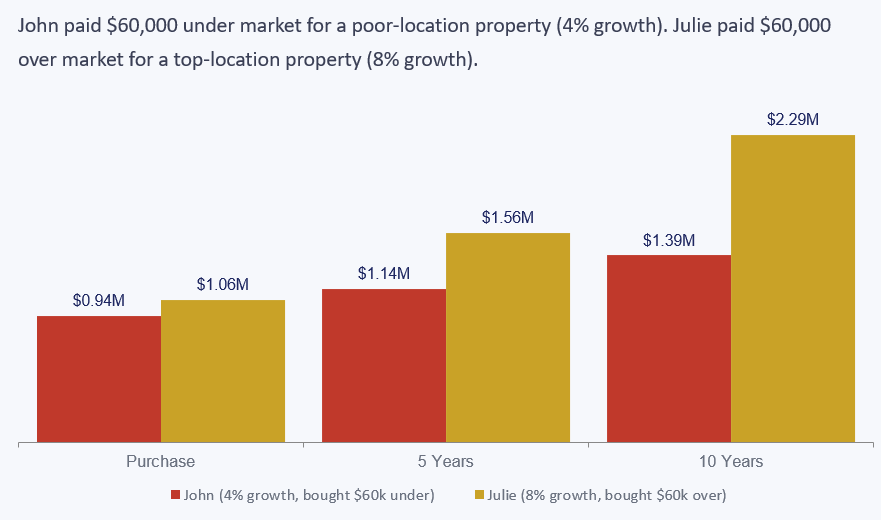
After a decade, the gap is almost $900,000.
The buyer who “overpaid” for a well-located property ends up far ahead, because quality is forgiving and compounding does the rest.
Even a 1% or 2% difference in annual growth becomes enormous over 10 or 20 years, especially with leverage.
Plenty of people are sitting on the sidelines right now, waiting for a sign.
By the time the media, your Uber driver and your hairdresser are all saying property is moving again, the opportunity has largely passed.
Delay costs more than the growth you miss, it also costs you the equity you could have drawn on to buy your next property.
Waiting slows the growth of your entire portfolio, not just that one purchase.
When to buy: reading the property cycle
There are five forces behind every Boom or Bust:
- Demographic demand, including new households and immigration
- Human psychology: fear of missing out, or fear of buying too early
- The availability of credit, which is tightening again on the back of rate rises
- Government policy. Last year’s home buyer grants pushed the market forward, and recent changes have pulled the rug out
- The global economy, including fuel prices, which we’re watching closely
Everyone is late to the party
Even experts like Michael Yardney and myself are late to the party sometimes.
One of the most valuable lessons Michael taught me is to invest when you are ready, with a long-term plan and the ability to act.
Markets bottom out quietly and there is never a neon sign that appears.
Nobody notices at the time, and public perception is that prices still have further to fall.
Meanwhile, strategic investors buying on research and long-term planning are already pushing prices forward.
By the time the public re-enters and sentiment turns positive, the market has already moved.
Think countercyclically
When everyone’s buying, the media is full of profit stories, FOMO is rife and prices are near their peak, while perceived risk is at its lowest, real risk is at its highest.
Over the past six to 12 months, we’ve been repositioning away from some of the markets that have done exceptionally well over the last five or six years.
Instead, we’re looking at markets where sentiment is gloomy and others are selling, because we know conditions will shift.
If you already hold assets in a hot market, a countercyclical purchase elsewhere can be a powerful move.
The bottom line
So, what, where and when should you buy? Here’s what it comes down to.
Preparation beats perfect timing. You don’t have to buy tomorrow, but you do need to be ready.
Location does 80% of the work. Prioritise it before anything else.
Buying right beats buying cheap. A quality asset in a strong location will outperform a bargain in a weak one.
Use a repeatable system. A proven, top-down process beats gut feel every time and buy in the right order.
The time will never feel perfect. Waiting has a real cost, and waiting for a feeling is just emotion.
Set yourself a deadline, commit to a time frame, and take action.
The investors who build lasting wealth aren’t the ones who timed the market perfectly, they’re the ones who followed a strategy, and took action while others were still waiting for a sign.
So what are you waiting for?